What Is a Warehouse Execution System (WES)? The Missing Middleware Behind Fulfillment Performance
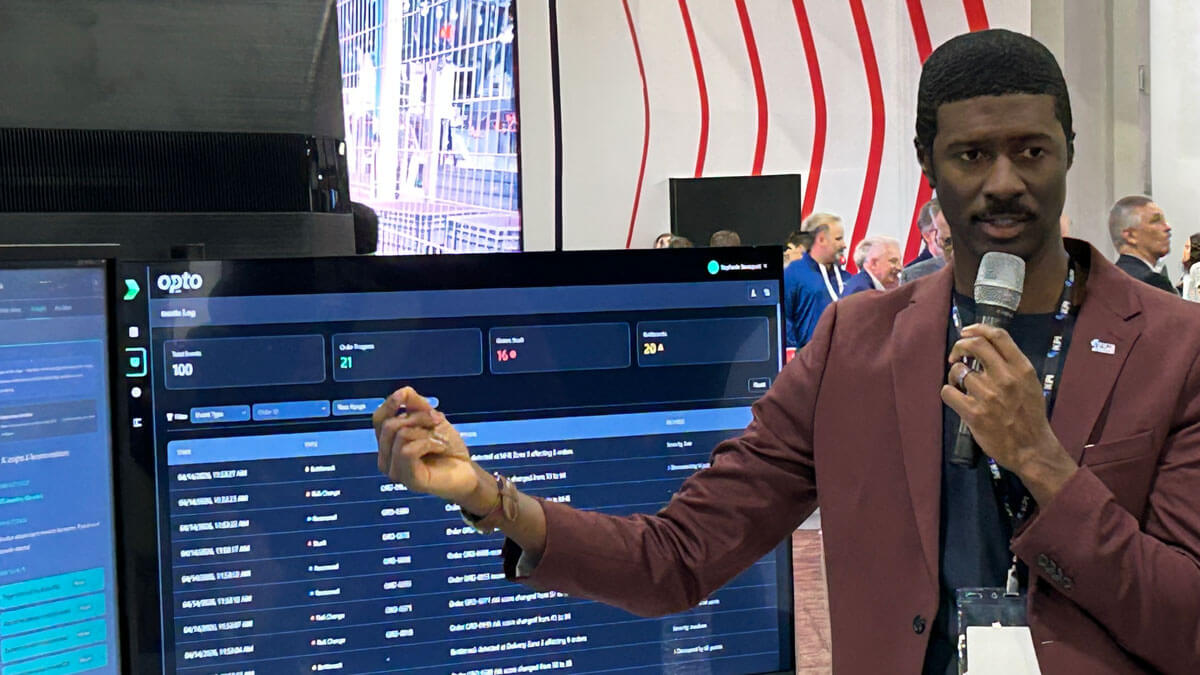
Every warehouse leader who has invested in automation has felt some version of the same disappointment: the conveyors run, the robots pick, the sortation sorts, and yet the operation still doesn’t move as fast as the business case promised. The equipment isn’t the problem. What’s usually missing is the software layer that tells it all what to do, in real time, based on what’s actually happening on the floor.
That layer is a Warehouse Execution System, or WES, and it’s become one of the most talked-about categories in supply chain technology this year, for good reason.
The Gap Between Planning and Doing
A Warehouse Management System (WMS) is built to plan: it allocates inventory, builds waves, and tells operations what needs to happen over a shift or a day. A Warehouse Control System (WCS), on the other hand, operates at the opposite end of the spectrum- milliseconds, not hours- driving the physical mechanics of conveyor, sortation, and robotics hardware.
A gap sits between those two layers. The WMS plans in batches; the floor changes by the minute. Labor calls out. An induction line jams. A rush order lands. Without something translating the WMS’s plan into second-by-second decisions the automation can act on, that gap is where fulfillment performance quietly erodes: orders slip, automation sits underutilized, and the ROI case for the equipment gets harder to defend.
That’s the job of a WES: it sits in the middle, orchestrating labor, automation, and inventory decisions in real time so the plan the WMS made in the morning still holds up by 2 p.m.
Why This is Suddenly Everywhere
Two numbers explain why WES has moved from a niche integration layer to a boardroom topic:
- Gartner projects that by 2028, roughly 80% of warehouses will have deployed some form of automation.
- The WES market itself is projected to grow from roughly $1.64 billion in 2024 to $4.28 billion by 2030.
Put simply: automation is no longer the differentiator it was five years ago. Nearly everyone is buying conveyors, robotics, and sortation. The differentiator is whether that automation is orchestrated well enough to actually deliver the throughput and labor savings it was purchased for. A warehouse with excellent hardware and no orchestration layer will consistently underperform one with modest hardware and a WES that’s actually doing its job.
What Good Orchestration Actually Does
At a practical level, a strong WES is making constant, real-time trade-offs that no static plan could anticipate:
- Balancing work across automation and labor as availability shifts hour to hour, not just at shift start.
- Re-sequencing priority when a rush order, a short-staffed shift, or an equipment slowdown changes what “on time” requires.
- Coordinating across vendors because most warehouses run automation from more than one manufacturer, and none of that equipment was designed to talk to the others natively.
- Feeding visibility back upstream so planning systems and the people running the operation both see the same real-time picture, not a report from yesterday.
Done well, this is invisible; the operation just runs. Done poorly, or not at all, it’s the reason a six- or seven-figure automation investment underdelivers for years.
Built Modular, Built to Scale
Part of what that Gartner recognition reflects is a deliberate architectural choice: Opto is built modular, not monolithic. Capabilities like labor orchestration, task interleaving, order sequencing, and robotics coordination are designed as components an operation can adopt incrementally; not a single all-or-nothing platform that has to be fully implemented before it delivers value.
That matters more than it might sound like on paper, for a few practical reasons:
- You don’t have to rip and replace to start. A facility can bring Opto in around existing systems and existing automation, rather than pausing operations for a wholesale platform swap.
- The platform grows the way the network grows. A single distribution center piloting orchestration on one automation line and a multi-site network coordinating dozens of facilities are running the same underlying architecture: scaled, not re-architected.
- New automation doesn’t mean a new integration project. As a network adds robotics, conveyor, or sortation from a new vendor, that capability extends into the existing orchestration layer instead of requiring a fresh build.
That modularity also makes vendor-neutral orchestration realistic rather than aspirational, which is worth addressing directly, since “vendor-neutral” is a claim a lot of software makes and fewer deliver on.
Why Vendor-Neutral, Proven-at-Scale Orchestration is Harder than it Sounds
Most warehouses run automation from more than one manufacturer, purchased at different times for different reasons. A genuinely vendor-neutral WES has to orchestrate it all as one coordinated resource pool without favoring any single manufacturer’s equipment, including one it may be commercially aligned with.
That’s a harder engineering and design problem than it sounds like, and it’s a big part of where we’ve focused Opto’s development: building orchestration logic that treats a conveyor line, a fleet of AMRs, and a sortation system as interchangeable categories of resource to be coordinated, not as separate silos each running their own local rules.
Why this matters right now is really a demand story, not a market-size one. The Gartner projection cited earlier is that roughly 80% of warehouses will be deploying some form of automation by 2028. This isn’t a statement about how large the WES software category will become; it’s a statement about appetite. Operators across more industries and more scales are choosing to automate for the first time, which means the population of warehouses that will need real orchestration is broadening faster than any one vendor’s existing footprint. A revenue projection tells you the category is real. Growing automation appetite across so many different kinds of operations is what actually tests whether a WES generalizes, and it’s the harder, more useful bar to clear.
That’s also where scale and market breadth become their own kind of proof. Orchestration logic that only has to work in one facility, one vertical, or one automation mix is a much easier problem than orchestration logic that has to hold up across grocery and retail fulfillment, food and beverage, 3PL, and industrial distribution, each with different order profiles, different seasonality, and different automation footprints. Opto’s deployments span that range, from single-site operations to multi-site enterprise networks, and that variability quickly exposes a platform’s limits if the underlying architecture isn’t genuinely flexible.
That combination, modular enough to adopt incrementally, neutral enough to orchestrate any vendor’s equipment, and proven across enough different markets and scales to have actually been tested by that variability, is the specific case we’d make for where Opto sits in this category, and it’s a theme we’ll keep building on through the rest of this series.
In the next post, we’ll go past the definition and into what real-time orchestration actually looks like inside a live warehouse, where the “AI is coming” conversation most vendors are having right now becomes something concrete.
Categories (tags):