The WES Market Doesn’t Have a Clear Leader Yet: Here’s Where We Think It’s Headed
It’s become a common observation across industry coverage of Warehouse Execution Systems (WES): this is a category without a settled leader. WMS vendors are extending into it. ERP companies are building toward it. Automation manufacturers are adding software layers on top of their own hardware. Independent integrators and platform providers, including us, are competing for the same ground. That’s an accurate read of where things stand and it’s worth being direct about what we think it means, rather than leaving the observation sitting there as a neutral fact.
An open category isn’t the same as an undifferentiated one. The providers who win it won’t be the ones who arrived first or who shout “AI” the loudest. They’ll be the ones who can prove three things: that they can orchestrate automation from vendors they didn’t build, that their software holds up under real operational variability rather than a clean demo environment, and that their roadmap is honest about what’s actually working today versus what’s still aspirational.
Why “Who Built the Automation” and “Who Orchestrates It” Are Different Questions
A natural assumption is that the company that sold you the conveyor or the robots is best positioned to also run the software coordinating them. In practice, the opposite is often true. A WES built by an automation manufacturer has an incentive, even if unstated, to favor its own equipment in how it allocates work. An operation running mixed automation from several vendors needs an orchestration layer with no allegiance to any one of them.
That’s the structural argument for platform providers and integrators in this category, and it’s the position we build from: Opto is designed to sit across heterogeneous automation, not to steer work toward a particular manufacturer’s hardware.
Why Proof Matters More Than Positioning Right Now
Every vendor in this space, ourselves included, is publishing some version of the same pitch: WES bridges planning and execution, automation without orchestration underperforms, the future is real-time and increasingly predictive. Read across the current wave of WES content and the pitch is nearly identical from company to company. That’s not a criticism of the argument, it’s true, but it means the argument itself is no longer a differentiator. Everyone has made it.
What’s still rare is public evidence: independent validation, and specificity about what a platform can and can’t yet do. That’s part of why we’ve pointed to Opto’s inclusion in the 2026 Gartner® Hype Cycle for Supply Chain Execution and Logistics Technologies Report throughout this series rather than leading with market-size projections the way most of this year’s WES content has. A market-growth statistic tells you the category is real. It doesn’t tell you which platform in it is worth betting on.s.
Where We’re Placing Our Bets
A few things we believe will separate the category’s winners over the next few years, and where we’re focused:
- Vendor-Agnostic Orchestration: That treats mixed automation fleets as a single coordinated resource, not a set of vendor silos with a dashboard layered on top.
- Honest, Incremental AI: Pattern-based prediction grounded in real operational history, built and validated in stages, rather than marketed ahead of what it can currently do.
- Integration Depth With IT Teams, Not Just Operations: The warehouses getting the most value from WES are the ones where the software fits cleanly into existing systems and support processes, not the ones bolting on another point solution.
- Proof Over Projection: Case results and independent recognition, not just category-level market statistics that every vendor in this space can cite equally.
The WES category is genuinely still being defined, and we don’t think that’s a bad thing. It means providers focused on real orchestration, real integration, and real evidence still have room to lead, rather than having to unseat an entrenched incumbent. That’s the case we’re building, one post and one customer result at a time.
See Opto in Action
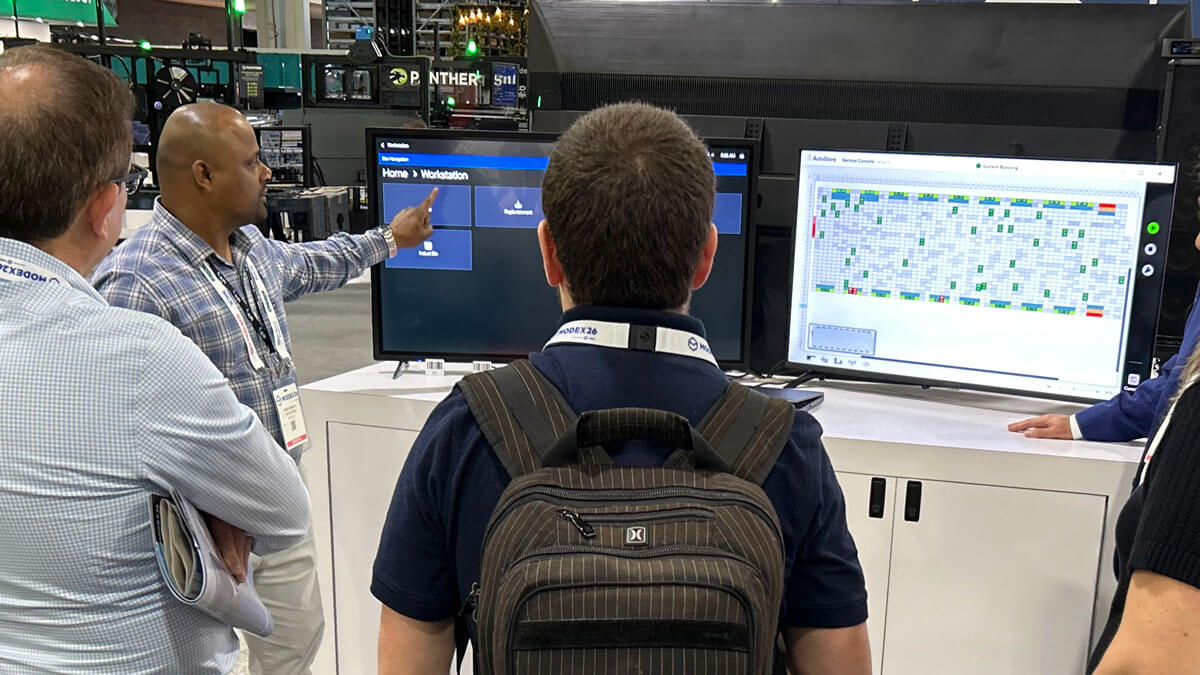
If you’re evaluating WES options against everything above, including an open market, a lot of nearly identical positioning, and no shortage of stats, the useful next step isn’t another market report. It’s a direct look at how Opto handles orchestration across mixed automation vendors, multiple sites, and the real operational variability a demo environment doesn’t show. This is backed by Opto’s inclusion in the 2026 Gartner® Hype Cycle for Supply Chain Execution and Logistics Technologies Report. Reach out, and we’ll walk through how Opto’s modular, vendor-neutral architecture would apply to your specific automation mix, not the category in the abstract.
Categories (tags):